About Klyris
Built by someone who files the same Anlage KAP.
Klyris started as my own problem: I trade futures through Interactive Brokers, and I had to turn the broker export into a correct Anlage KAP. Classify Termingeschäfte properly, convert every position into euros at the right day's rate, keep the loss-offset pots (Verlustverrechnungstöpfe) separate, and be able to back up every figure if the Finanzamt asks. Doing that by hand is slow and error-prone; Klyris is the tool I was missing. I use it for my own figures, and you get the same documents.
How to check the figures yourself
Klyris is built so you can recompute the figures yourself. What you can check:
- The positions in the audit trail sum exactly to the Anlage KAP summary. That reconciliation runs on every pass; if it does not add up, the output says so.
- During development, the futures results were reconciled per closing transaction against IBKR's own reported realized P/L, on real account data.
- Currency conversion uses the reference rates of the European Central Bank, per position at the relevant date; the audit trail names the rate used for every figure.
Drop your own IBKR Flex export into the live preview, or start with the sample, and look at the reconciliation. The computation runs in your browser and the file stays on your device.
Recompute it with your own fileWhat Klyris is not
Just as important as what Klyris does:
- Klyris is not tax advice. It computes and documents; individual tax questions belong with a tax professional, and the responsibility for your return stays with you.
- Most complete for futures and options (Termingeschäfte and Stillhaltergeschäfte).
- Stock sales, dividends, credit interest and creditable US withholding tax are computed, not yet externally assessed. Funds (Anlage KAP-INV) are not included.
- Klyris submits nothing to ELSTER. You transfer the figures into your return yourself and stay in control.
Klyris is a software tool, not tax advice.
Where Klyris is going, and what will not change
Klyris is meant to become the reliable place for capital income from foreign brokers: Termingeschäfte first, then the whole Depot, step by step. The scope grows under four rules that do not change:
- Klyris markets a new area as part of the product only once its tax conventions have been assessed externally. Until then it computes that area visibly as a preview and says so in every document.
- What Klyris cannot classify, it names and leaves out of the computation. Nothing is guessed. Better a line that says "not evaluated" than a figure without a derivation.
- Your file stays on your device. No future feature changes that: anything that would need a server does not go into the product.
- Klyris does not promise how the Finanzamt will decide. Nobody can. What Klyris does promise: every figure can be checked, derived down to the broker row and reconciled against the broker's own result.
And if Klyris is gone one day? The computation runs in your browser and depends on no service. The documents you generated stay with you, with the engine version and checksums on them.
Who is behind it
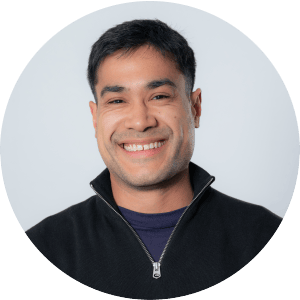
Klyris is developed and run by me: Andreas Haas, software developer, self-employed since 2022 and full time since 2025. Klyris is currently my full-time work. There is no team or agency behind it, and I answer your questions myself.
Legal basis in the dossier
Externally assessed: a tax firm specializing in Termingeschäfte has given a professional assessment of the tax conventions (forwards and option-writing, from tax year 2024, legal position after the JStG 2024). This concerns the method, not the software and not the individual figures. Klyris evidences the arithmetic separately, to the cent against the broker P&L.
Every tax convention Klyris applies is stated with its legal basis in the generated Steuerberater dossier: statute, BMF circular, margin number. One example:
Futures are recognized as one cash settlement (Differenzausgleich) at close-out or expiry: § 20 Abs. 2 Satz 1 Nr. 3 Buchst. a EStG, § 20 Abs. 4 Satz 5 EStG; BMF circular of 14 May 2025, margin no. 36.
The live preview generates the full dossier with every legal citation after each run, including with the bundled sample. View the dossier in the live preview